 Written by
 Edited by
 Edited by

If you’re looking for a financial advisor, Form ADV is an essential point of reference. This publicly available paperwork must be filed with the U.S. Securities and Exchange Commission (SEC) by investment advisory firms required to register with the SEC. Form ADV includes dozens of pages of information about a firm. This includes its fee structure, total assets under management, other business activities, any disciplinary issues on record and more.
A financial advisor can help you with retirement and estate planning, investment portfolios, taxes and more.
What Is Form ADV?
Form ADV is officially called the Uniform Application for Investment Adviser Registration and Report by Exempt Reporting Adviser. Investment advisors generally register with either the SEC or state securities regulators, depending on their regulatory assets under management and other eligibility requirements. Most advisors with less than $100 million in regulatory assets under management register with state regulators, although exceptions apply. Advisors with at least $110 million generally must register with the SEC, while those with $100 million to $110 million may generally choose between SEC and state registration, subject to applicable rules. Registered advisors must update their Form ADV annually.
Form ADV includes three parts, although not every firm must complete all three. Part 1 is a fill-in-the-blank form, and Part 2 is a brochure written in prose. The first part contains basic facts about the firm, like its fees, client types, assets under management and any disclosures. The second part explains its services, investing approach and any conflicts of interest. Part 3, also known as Form CRS, is a brief relationship summary required for SEC-registered investment advisors that provide services to retail investors. It describes services, fees, conflicts of interest and disciplinary history.
Form ADV provides a wealth of information about registered firms. Potential clients should always review a firm’s Form ADV before they begin to work with the firm.
The SEC paperwork provides information that most firms don’t disclose on their websites. This includes whether they have any disclosures, charge performance-based fees, or earn commissions from selling products to clients. It may not always be clear when a firm last updated its website, but firms must update Form ADV annually and make certain amendments when information changes. Annual updating amendments are generally due within 90 days after the firm’s fiscal year ends.
Breaking Down Form ADV Part I
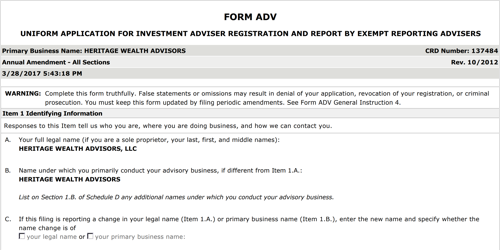
As mentioned, Part I of Form ADV is a fill-in-the-blank form. It can range from 15 pages to over 100, depending on the firm’s disclosures.
Form ADV Part I is divided into at least 12 items. The first section establishes basic information about a firm. You’ll find things like its legal name, the name it does business under, its address, website and phone number.
Items 3 through 7 provide a wealth of information for prospective clients. This is where the firm lists:
- Total assets under management
- Total number of accounts
- Number of employees serving in an advisory function
- Percentages of each client type it serves (including individuals versus high-net-worth individuals)
- Compensation arrangements (the financial advisor fees it charges for services)
- Advisory activities (whether it provides financial planning, portfolio management, etc.)
- Other business activities (whether it’s also an insurance broker or broker-dealer)
Another notable section of the Form ADV Part I is Item 11. In this section, the firm reveals whether it has any reportable disciplinary events on its record. If it does, the firm must state what its offenses were and whether they involved any supervised persons. The firm must also attach a report that provides further detail on any affirmative response. 1
Breaking Down Form ADV Part II
The SEC often labels this part of Form ADV as “Part 2 Brochures.” Part II of Form ADV contains a table of contents, which makes it easier to navigate than Part I.
Like the first part, Part II is divided into various items, with 18 items in total in the Part 2A firm brochure. Part 2B contains brochure supplements with information about certain individuals who provide investment advice to clients.
Part II: Items 1-8
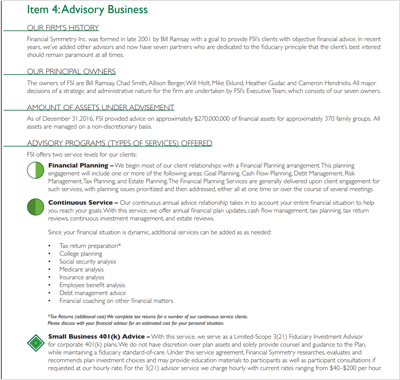
The first eight items of Form ADV Part II typically contain the most relevant information for prospective clients. The first few items include the cover page, any changes that have occurred since the firm’s last filing and the table of contents. The true beginning of Part II is Item 4, which offers an overview of the firm. This is where you can find the firm’s founding year, its owners and the services it provides.
Items 5 and 6 cover the firm’s fees. Item 5 outlines the exact fees a firm charges for its various services. Item 6 makes clear whether the firm charges performance-based fees or offers side-by-side management.
A particularly important item to consider is Item 7, where the firm describes its typical clients and often lists its account minimum. Item 8 provides a deep dive into the firm’s methods of analysis and investment strategies, as well as a warning of the risks involved with investing. This is where you can gain a better understanding of how the firm invests its clients’ assets and what investment types it typically uses.
Part II: Items 9-18
These items provide information about the firm’s inner workings and policies. Item 9 provides more details on any disciplinary information, while Item 10 discloses any other financial industry activities and affiliations. You can usually find out in Item 10 whether a firm earns commissions from selling insurance products or securities.
Item 11 is the firm’s code of ethics and Item 12 details a firm’s brokerage practices. The remaining sections outline a firm’s policies on account reviews, client referrals, custody of clients’ assets, voting client securities and any other relevant financial information. 2
Understanding Form ADV Part III
Part 3 of Form ADV, commonly called Form CRS, or the customer relationship summary, gives retail investors a shorter overview of an advisory firm’s services and potential conflicts of interest. SEC-registered investment advisors that serve retail investors generally must prepare and deliver this document. Broker-dealers serving retail investors also have Form CRS requirements.
Form CRS describes the services a firm offers, the fees and costs investors may pay, the firm’s legal obligations to clients and any reportable legal or disciplinary history. It also includes suggested questions investors can ask before entering into an advisory relationship.
Unlike the longer Part 2 brochure, Form CRS is designed to help investors compare firms without reading extensive regulatory disclosures. An investment advisor’s relationship summary is generally no more than two pages, while a combined summary for a firm offering both advisory and brokerage services may be up to four pages.
Firms must update Form CRS and file an amendment within 30 days whenever information in the document becomes materially inaccurate. They must also communicate those changes to existing retail investors within 60 days of when that update becomes necessary.
Reading Form CRS alongside Parts 1 and 2 can help you identify important differences between firms. For instance, one firm might provide ongoing investment management for an annual asset-based fee, while another offers transaction-based brokerage services that generate commissions. Form CRS can help you recognize those distinctions before reviewing the more detailed fee disclosures in Part 2.
How to Access a Firm’s Form ADV
Form ADV is publicly available through the SEC’s Investment Adviser Public Disclosure website. On this website, you can search for individual advisors and advisory firms by either the firm or advisor’s name or their Central Registration Depository (CRD) number. The CRD number is a unique identifier used in the securities industry’s registration system. CRD stands for Central Registration Depository, a database that contains information about firms and brokers.
Many firms also provide a link to their Form ADV on their websites. An investment advisory firm should also be able to provide its brochure upon request.
What to Look for When You Pull a Firm’s Form ADV
Once you have the form in front of you, the disclosure history is a good place to start. Firms must report disciplinary and legal events that meet Form ADV’s disclosure requirements. This may include certain regulatory actions, arbitration proceedings and client complaints, though a firm may not have to report every complaint or dispute. When looking things over, keep in mind that a single resolved matter from years ago looks different than a pattern of recurring issues. The specifics tell you more than the presence or absence of a disclosure alone, so read what actually happened before drawing conclusions.
The compensation section is also worth your time. This shows the different ways a firm gets paid. Some firms charge a percentage of assets. Others bill hourly, collect flat retainers or earn commissions on the products they recommend. A firm that collects fees from you and commissions from product providers has a built-in tension that you should understand before signing on. That doesn’t make the firm dishonest, but it does mean you should ask how it decides when to recommend a commissioned product over one that doesn’t pay the firm anything extra.
Client Data and Strategy
The form breaks down the firm’s client base by category, showing what percentage are individuals, high-net-worth investors, institutional clients or retirement plans. This tells you whether you’re the type of client the firm is built to serve. A firm where 85% of accounts belong to institutional investors may not have the infrastructure or interest to give a retail client with a $400,000 investment portfolio the attention they expect. Knowing where you fit in the client mix before your first meeting saves everyone time.
You can also calculate a rough client-to-advisor ratio from the numbers reported in the form. Total accounts divided by advisory employees gives you a sense of how stretched the team is. A firm managing 4,000 accounts with six advisors is running a volume practice, which often means standardized portfolios and limited customization. However, the ratio alone does not establish the level of service clients receive because firms may use different staffing models and support teams. That model works well for some people and poorly for others, but the form gives you the data to know what you’re walking into.
The investment strategy section describes how the firm manages money, what types of securities it favors and how it thinks about risk. If you have strong feelings about active versus passive management, alternative investments or concentrated stock positions, this is where you find out whether the firm’s approach matches yours. Reading this section before an introductory call means you spend less time on basics and more time on the questions that actually matter to your decision.
What Form ADV Doesn’t Tell You
While Form ADV provides transparency on an advisor’s fees, conflicts of interest and regulatory history, it has limitations. It doesn’t always reveal an advisor’s investment philosophy, client service approach or communication style. These are all factors that can significantly impact a client’s experience. Additionally, while disciplinary disclosures are included, they may lack context. This can make it difficult to assess the severity of past infractions.
As such, consumers should supplement Form ADV with additional research. Reading client reviews, asking about real-life case studies and conducting interviews can provide insight into an advisor’s approach. Requesting a sample financial plan or discussing how an advisor tailors strategies to different client needs can also help.
Since Form ADV doesn’t highlight ongoing service commitments, prospective clients should clarify how frequently an advisor communicates, whether they proactively adjust strategies, and how they handle market downturns.
Tips for Reading Form ADV
Form ADV contains valuable details, but knowing where to focus can make reviewing it more effective.
Start with Part 2, which is written in plain language and outlines the advisor’s services, fees, and conflicts of interest. Pay attention to Item 5, which explains how the advisor charges clients—whether through a flat fee, hourly rate, or percentage of assets under management (AUM).
Next, check Item 9 for any disciplinary disclosures, but research further to understand the severity and context. In Item 10, look for affiliations with other financial firms, which could indicate potential conflicts of interest.
Part 1, while more technical, provides details on assets under management and ownership structure. This information can help assess the firm’s stability.
If the firm serves retail investors and is required to provide Form CRS, review that document as well. It can help you compare services, fees and conflicts across firms before examining their more detailed disclosures.
Top Financial Advisors By City and State
If you’re interested in the information within Form ADV and want to choose a financial advisor based on it without having to read through the form yourself, consider using our top Financial Advisors tool. This will enable you to sort by city and state to find financial advisors who serve your area and review their qualifications, services and available disciplinary information. You can even find a financial advisor that specializes in the service you need the most.
Bottom Line
Form ADVs are available through the SEC and remain some of the most valuable resources for investors. They allow you to learn about a firm’s services, fees and investment strategies. This can, in turn, help you make a more informed decision when choosing a firm to invest your money with.
Tips for Choosing a Financial Advisor
- There are many different financial advisors you can work with, and that can make choosing one quite difficult. SmartAsset’s free tool matches you with financial advisors who serve your area, and you can have a free introductory call with your advisor matches to decide which one you feel is right for you. If you’re ready to find an advisor who can help you achieve your financial goals, get started now.
- Any firm that registers with the SEC must abide by fiduciary duty, which means it must act in clients’ best interests at all times. Therefore, looking for a fiduciary financial advisor is extremely important.
- Try to find an advisor who has certifications to their name. A certified financial planner (CFP) is one of the most prestigious designations and requires extensive experience and effort to obtain.
Photo credit: ©iStock.com/JohnnyGreig, https://adviserinfo.sec.gov/
Article Sources
All articles are reviewed and updated by SmartAsset’s fact-checkers for accuracy. Visit our Editorial Policy for more details on our overall journalistic standards.
- Securities and Exchange Commission. https://www.sec.gov/files/formadv-part1a_1.pdf. Accessed Apr. 16, 2026.
- Securities and Exchange Commission. https://www.sec.gov/files/formadv-part2_0.pdf. Accessed Apr. 16, 2026.